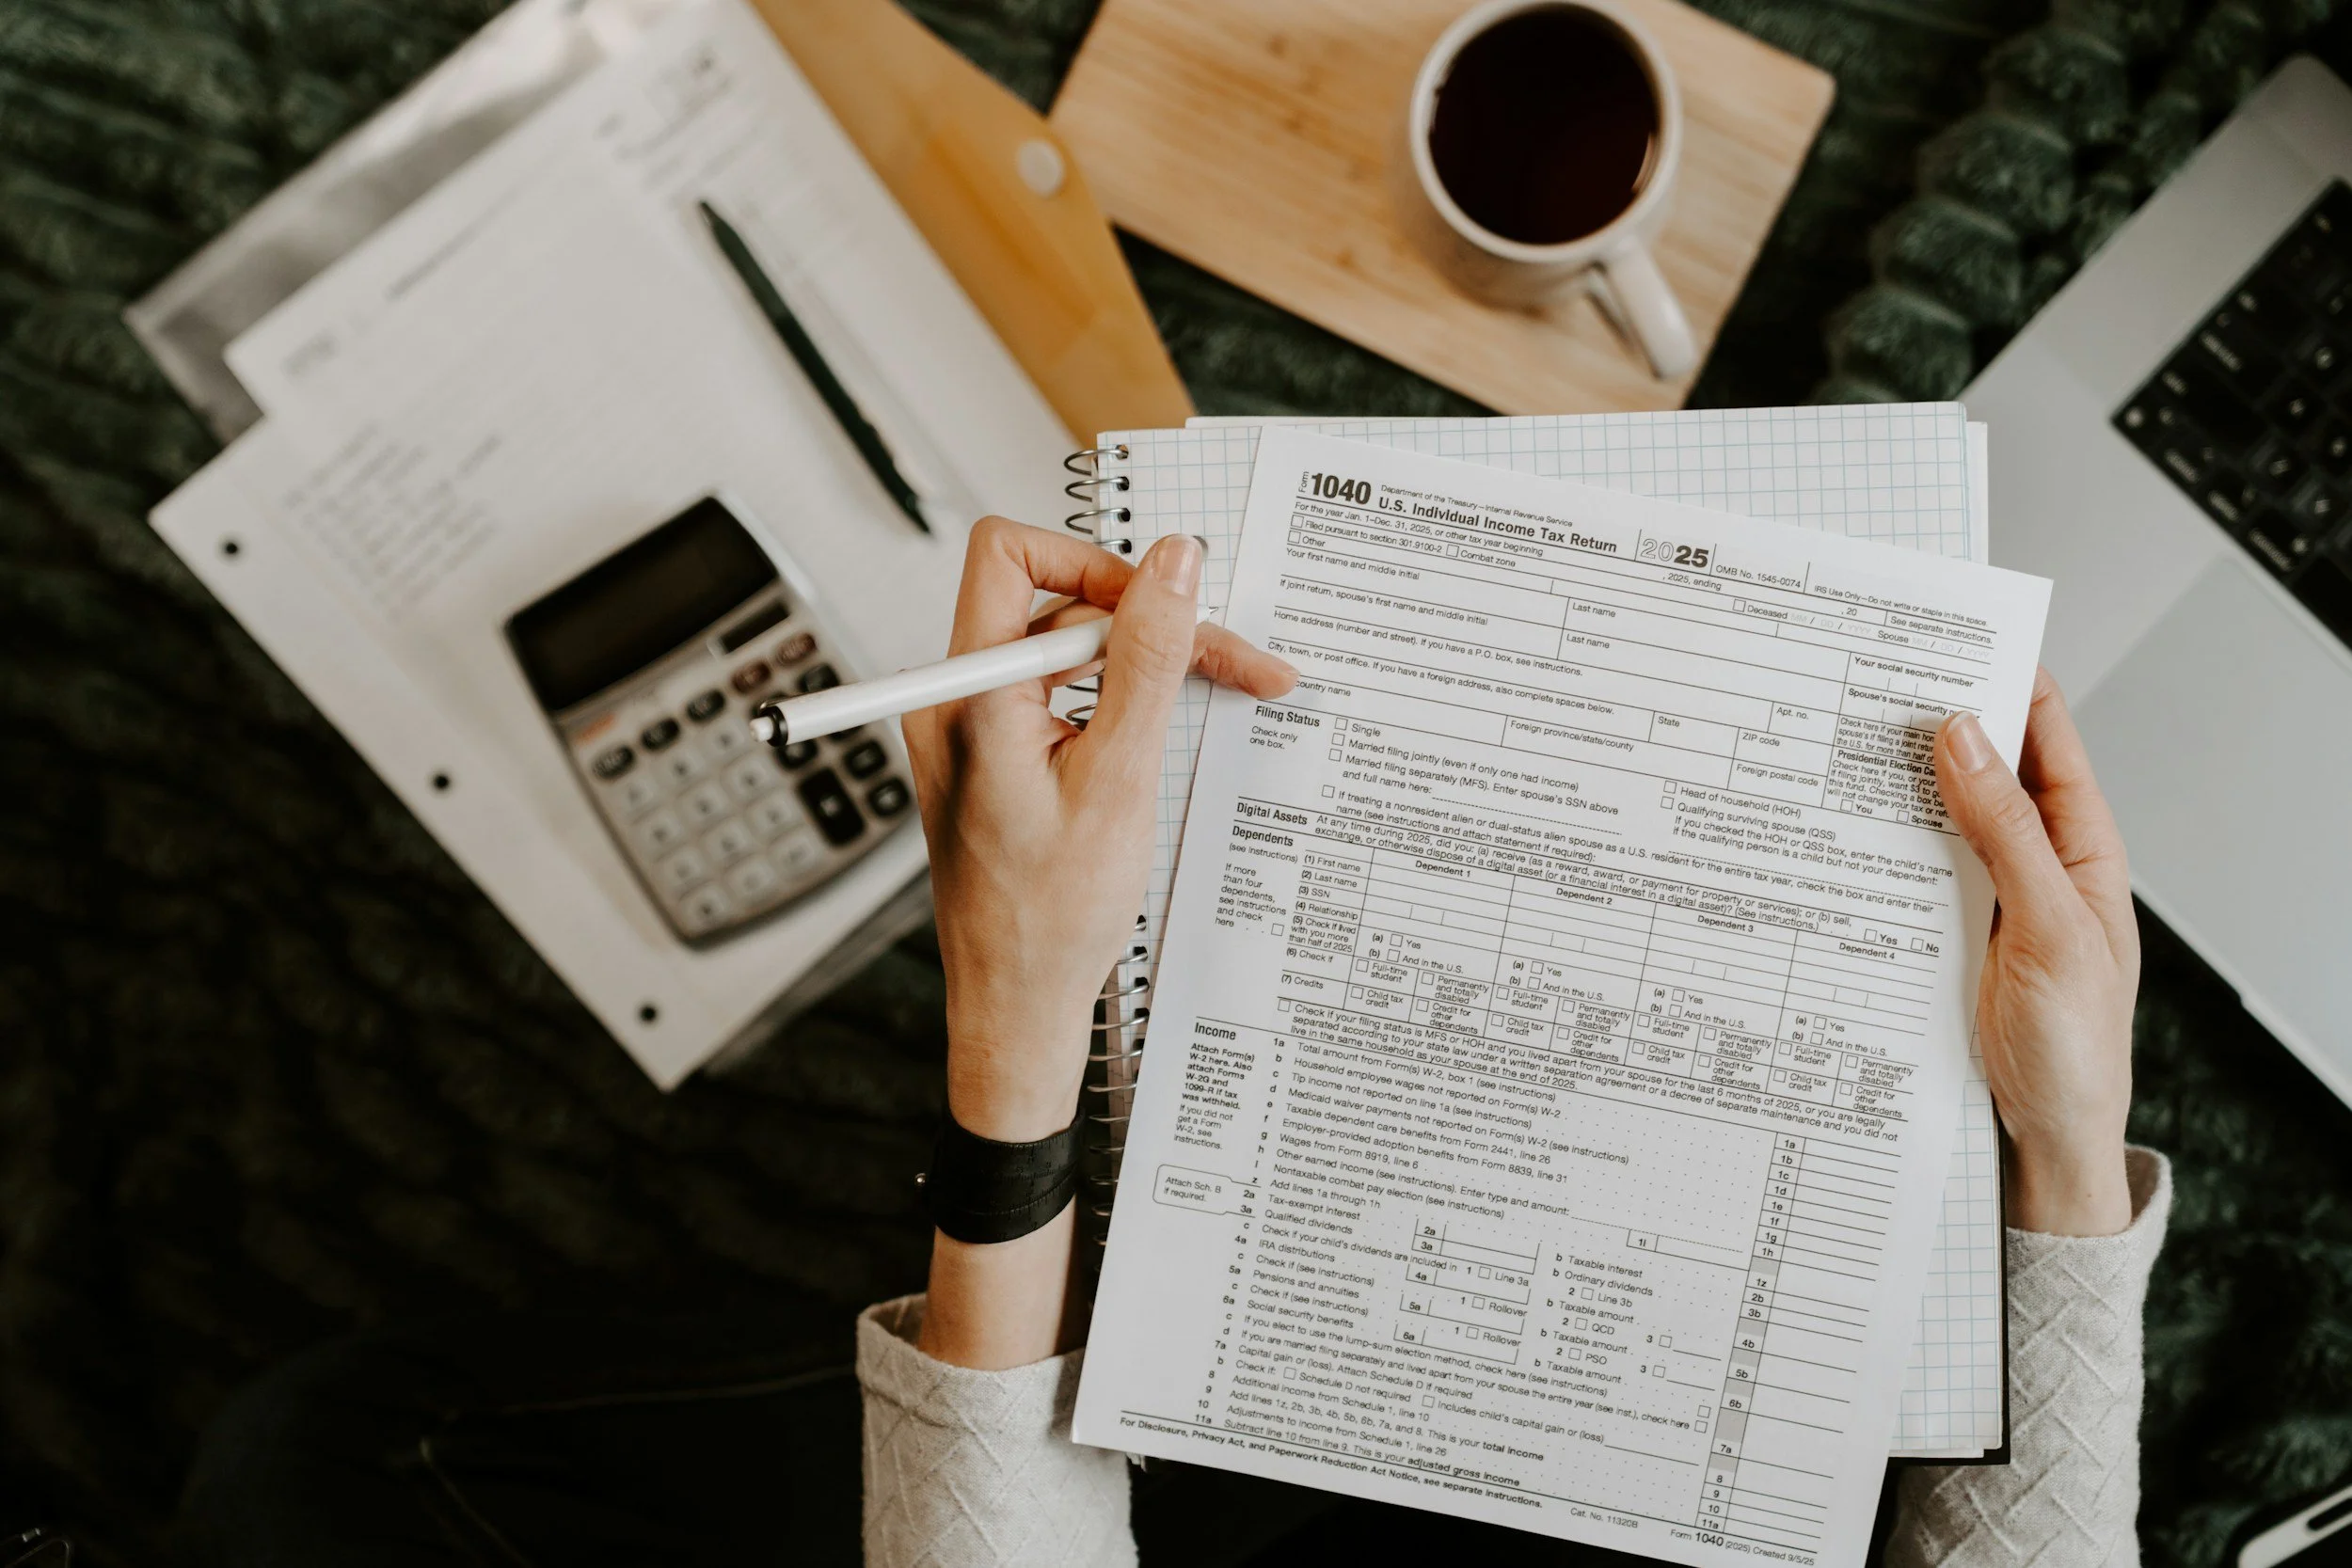



For business owners, the line between company finances and personal finances can be thin. Profits from a pass-through business flow onto your personal return. How you pay yourself affects payroll taxes. A retirement plan for the company can be one of your largest personal deductions. A decision made for the business often shows up on your Form 1040.
Tax planning for business owners looks at those connections throughout the year, not only when returns are filed. This guide outlines the main areas owners review with their CPAs and financial advisors, so you can approach those conversations with a clearer picture.
Start With Entity Structure
How a business is organized affects how its income is taxed.
Sole proprietorships and single-member LLCs: Business income is reported on the owner's return and is generally subject to self-employment tax.
Partnerships and multi-member LLCs: Income passes through to the owners based on the partnership agreement.
S corporations: Income passes through to shareholders. Owners who work in the business generally must take reasonable wages, which are subject to payroll taxes, while remaining profits may be distributed without payroll tax.
C corporations: The company pays corporate income tax, and shareholders pay tax again on dividends. C corporation stock may qualify for qualified small business stock treatment if requirements are met.
Changing entity type can have tax costs and legal consequences, so it is usually reviewed with a CPA and attorney.
Owner Compensation
For S corporation owners, setting a reasonable salary is a balance. Wages that are too low can draw IRS scrutiny, while higher wages increase payroll taxes but may raise the amount that can be contributed to some retirement plans. The right level depends on the role, industry norms, and plan design.
The Qualified Business Income Deduction
Owners of pass-through businesses may be eligible for a deduction of up to 20% of qualified business income under Section 199A. Legislation passed in 2025 made this deduction permanent. Limits apply at higher incomes, particularly for specified service businesses such as health, law, consulting, and financial services, and wages paid and property held by the business can affect the calculation.
Retirement Plans as a Tax Tool
Retirement plans can allow owners to set aside income on a tax-deferred basis while also offering a benefit to employees.
SEP IRAs: Employer contributions based on a percentage of pay. Annual limits apply.
401(k) plans: Employee deferrals plus employer contributions, with safe harbor designs that can simplify testing.
Cash balance plans: A type of defined benefit plan that can allow larger deductible contributions for some owners, with required annual funding.
Combined designs: Pairing a 401(k) with profit sharing or a cash balance plan can increase total contributions, subject to testing.
Owners of more than one business should also consider whether the companies form a controlled group, which can affect plan testing and limits.
State Taxes and the Pass-Through Entity Tax
The federal deduction for state and local taxes paid by individuals is limited. California has offered an elective pass-through entity tax that allows eligible partnerships and S corporations to pay state tax at the entity level, which can change how much of that tax is deductible federally. Rules, deadlines, and availability can change, so owners can confirm each year with their CPA.
Deductions and Timing
Equipment and Depreciation
Purchases of equipment and certain property may be deducted over time or, in some cases, more quickly through bonus depreciation or Section 179 expensing. Rules changed under 2025 legislation, and the timing of purchases can affect which year receives the deduction.
Accounting Method and Year-End Timing
Businesses using the cash method may be able to time some income and expenses near year-end. Accrual-method businesses have different rules.
Health Coverage
Self-employed owners may be able to deduct health insurance premiums, and health savings accounts can offer tax advantages when paired with a qualifying high-deductible plan. Annual limits apply.
Business Expenses
Ordinary and necessary expenses, including a home office, vehicles, and travel, may be deductible when properly documented. Accountable plans can help reimburse owner-employees for business costs.
Estimated Taxes and Cash Flow
Business owners often pay tax through quarterly estimated payments rather than withholding. Underpaying can lead to penalties. A mid-year projection can help match estimated payments to actual results and reduce the chance of an unexpected balance due when the return is filed.
Planning Ahead for an Exit
Tax outcomes can be shaped years before a business is sold. Entity type, how long stock has been held, the structure of a future sale, and the owner's state of residence can all affect the eventual tax bill. Owners who expect to sell may want to bring their CPA, attorney, and financial advisor together well before a letter of intent arrives.
Keeping Business and Personal Planning Connected
Owners whose wealth is concentrated in their business may want to look at how the company's tax strategy fits with personal goals, such as building savings outside the business, funding education for children, or preparing an estate plan. Our article on your biggest financial decision may not be an investment decision explores how non-investment choices can shape long-term results.
A Year-Round Planning Rhythm
Early in the year: Review the prior year's results and set estimated payments.
Mid-year: Run a projection, revisit owner compensation, and confirm retirement plan funding targets.
Fall: Review equipment purchases, pass-through entity tax elections, and year-end timing.
Year-end: Complete planned contributions, purchases, and payroll adjustments.
Questions to Bring to Your CPA
Is my entity structure still a fit? Has the business grown or changed in a way that affects that choice?
Is my salary reasonable? How does it affect payroll taxes and retirement plan limits?
Do I qualify for the QBI deduction? What limits apply to my type of business?
Is the pass-through entity tax available and useful for me this year?
Which retirement plan design fits my goals? What would different designs cost?
How Auric Supports Business Owners
Auric Capital Partners works with business owners on decisions that range from running a liquidity event to planning for retirement. Its tax minimization strategies aim to help planning decisions support after-tax outcomes, its self-employed retirement services focus on retirement solutions that fit an owner's cash flow and business structure, and its exit strategies service helps owners prepare for and navigate transitions. Tax preparation and formal tax advice remain with the owner's CPA.
For entrepreneurs and independent professionals, the aim is to connect company decisions with the personal plan behind them. See the firm's services.
Let's Connect
If you want your business tax decisions and your personal financial plan to work together, we would be glad to talk. Contact our team to arrange a meeting in Aliso Viejo or virtually. No scripts, no pressure.
Frequently Asked Questions
What is tax planning for business owners?
It is the process of reviewing entity structure, owner compensation, retirement plans, deductions, and timing to understand how business decisions affect both company and personal taxes.
What is the qualified business income deduction?
Section 199A allows eligible owners of pass-through businesses to deduct up to 20% of qualified business income, subject to limits at higher incomes. Legislation passed in 2025 made the deduction permanent.
How much salary should an S corporation owner take?
Owners who work in the business generally must take reasonable compensation based on their role and industry norms. A CPA can help evaluate what is reasonable.
What is the California pass-through entity tax?
It is an elective tax that allows eligible partnerships and S corporations to pay California tax at the entity level, which can affect federal deductions for state taxes. Availability depends on current state law.
Which retirement plan is a fit for a business owner?
It depends on income, employees, cash flow, and savings goals. Options include SEP IRAs, 401(k) plans, and cash balance plans, sometimes in combination.
This content is for educational and informational purposes only and should not be considered investment, tax, or legal advice. It is not a recommendation to buy or sell any security or to adopt any particular investment strategy. Investing involves risk, including the possible loss of principal. Past performance is no guarantee of future results, and no strategy can guarantee a profit or protect against loss. Please consult with a qualified professional about your individual situation. Registered Representative of Sanctuary Securities Inc. and Investment Advisor Representative of Sanctuary Advisors, LLC. Securities offered through Sanctuary Securities, Inc., Member FINRA, SIPC. Advisory services offered through Sanctuary Advisors, LLC., a SEC Registered Investment Adviser. Auric Capital Partners is a DBA of Sanctuary Securities, Inc. and Sanctuary Advisors, LLC.